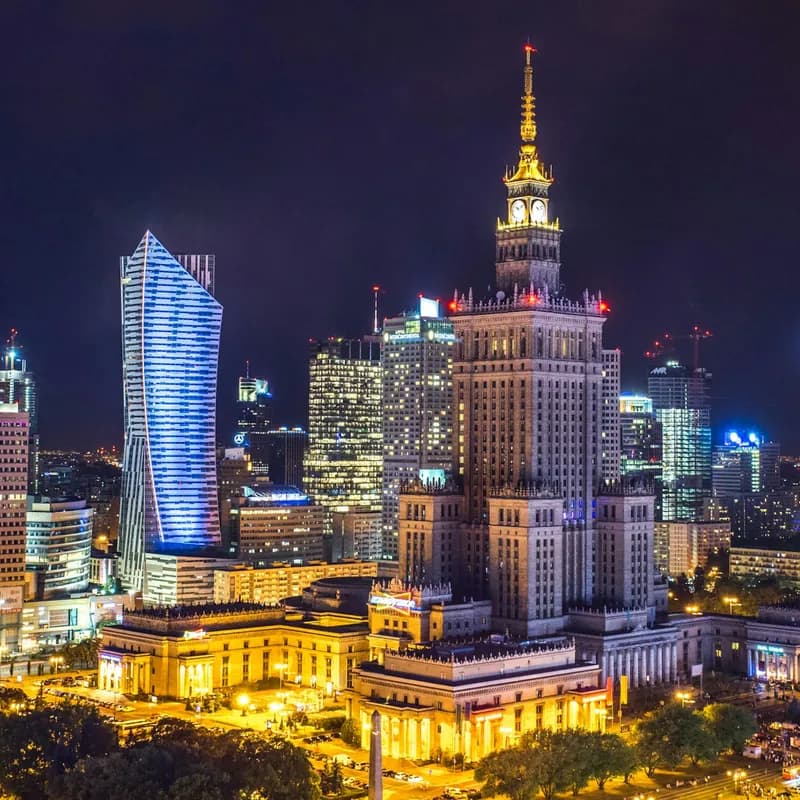
Poland is the largest economy in Central Europe and the sixth largest in the European Union, and it has become the natural entry point for companies that want an EU base with Western-standard institutions and Central-European costs. Formation is genuinely quick — an online registration can produce a working company in about a day — but the value of a Polish structure lies in what follows: the right tax regime, a clean VAT position and a reporting calendar that the tax administration increasingly reads in real time.
1.Choosing the Right Legal Form: sp. z o.o., P.S.A., S.A. and Partnerships
Polish company law is codified in the Kodeks spółek handlowych (Commercial Companies Code), and foreign investors may use every form it contains.
Spółka z ograniczoną odpowiedzialnością (sp. z o.o.) — the limited liability company, chosen in the overwhelming majority of foreign investments. Minimum share capital is PLN 5,000, with a nominal value of at least PLN 50 per share. Management sits with the zarząd (management board), whose members may hold any nationality and need not live in Poland, and a single shareholder may own the whole company. A supervisory board is compulsory only where capital exceeds PLN 500,000 and there are more than twenty-five shareholders.
Prosta spółka akcyjna (P.S.A.) — the simple joint-stock company, available since July 2021 and built for startups. Share capital starts at PLN 1, shares have no nominal value, and contributions may take the form of work or services, which is impossible in the other capital companies. It also permits a single-tier rada dyrektorów in place of separate management and supervisory boards, though banks and trading partners know it less well.
Spółka akcyjna (S.A.) — the full joint-stock company: minimum capital PLN 100,000, at least a quarter paid before registration, a mandatory supervisory board and notarial formalities throughout. Reserved for large operations and public offerings.
Partnerships — the spółka jawna (general partnership, partners liable without limit) and the spółka komandytowa (limited partnership, with at least one general and one limited partner); since 2021 the komandytowa is itself a CIT payer, which removed most of its former tax appeal.
For nearly every foreign investor the answer is the sp. z o.o.: cheap to form, recognised everywhere and compatible with every regime described below.
2.Two Routes to Incorporation: the S24 System or a Notarial Deed
Poland offers two genuinely different formation paths, and choosing correctly at the outset saves both money and rework.
The S24 route. The Ministry of Justice operates an online system in which a sp. z o.o., a P.S.A. or most partnerships are created from a template deed (wzorzec umowy) and registered by the court, in principle, within one business day. The trade-offs are strict: the articles may only be assembled from the options the template offers, and contributions must be in cash. Every shareholder and board member signs electronically with a profil zaufany (the Polish trusted profile), a Polish e-dowód or a qualified electronic signature; a founder abroad without a Polish PESEL number uses the last option, since any eIDAS-qualified signature issued in the EU is accepted. Court and announcement fees come to roughly PLN 350 as of 2025.
The notarial route. A Polish notary is required whenever the articles depart from the template — share classes with different rights, tailored transfer restrictions, non-standard majorities — or whenever capital is contributed in kind (aport). Founders need not attend: a notarised, apostilled power of attorney, translated by a sworn translator (tłumacz przysięgły), lets a representative sign in Warsaw. The filing is still electronic, through the Portal Rejestrów Sądowych, since all KRS filings became digital in July 2021. Fees are roughly PLN 600 plus the notary's scaled charge.
Transfer tax. In both cases the articles attract PCC at 0.5% of share capital. The notary collects it on the traditional route; on S24 the company files a PCC-3 return and pays within fourteen days itself — the step first-time founders most often miss.
3.KRS Registration, NIP, REGON and the Beneficial Owner Register
The KRS. A Polish company comes into full legal existence on entry in the Krajowy Rejestr Sądowy (KRS), the National Court Register kept by the commercial division of the district court for the company's seat. Between signature and entry it already trades as a spółka z o.o. w organizacji, able to open a bank account, sign contracts and employ people under that suffix. The register is public and free to search: it shows the board and the manner of representation, the share capital, the business scope and every shareholder holding 10% or more of the capital.
NIP and REGON arrive automatically. Under the one-stop-shop principle the court transmits the registration to the statistical office and the tax administration, which issue the REGON statistical number and the NIP tax identification number without a separate application, usually within days.
The NIP-8 filing. Data the court does not collect — bank account numbers, the place where accounting records are kept, additional operating addresses — goes to the tax office on form NIP-8 within 21 days of the KRS entry, or within 7 days if the company starts paying social insurance contributions sooner.
The CRBR. Every company reports its beneficial owners to the Centralny Rejestr Beneficjentów Rzeczywistych, the Central Register of Beneficial Owners, within 14 days of the KRS entry and within 14 days of any later change. The notification is electronic and must be signed personally by board members in line with the company's representation rules — a proxy may not file it. Penalties reach PLN 1,000,000, so the deadline belongs in the diary on the day the company is registered.
4.Share Capital, the Registered Address and the Bank Account
Share capital in practice. The PLN 5,000 minimum is working capital, not a blocked deposit — it may be spent on the business from day one. On the traditional route it is contributed before the application is filed and the board declares it in the filing; on S24 contributions may follow registration, with the board declaring them within seven days of the entry. Capital contributed in kind must be described in the articles — the asset, the contributor and the shares issued in exchange.
The registered address. The articles state the siedziba — the town that determines which court and which tax office handle the company — while the exact address is reported to the register. The court expects evidence of a right to use the premises: a lease, a title deed, or a written consent from the person holding title to the address. Virtual offices are widely used and generally accepted, but choose the provider carefully: tax offices verify addresses when processing VAT registrations, and an address with no capacity to receive correspondence or host an inspection invites refusal or later deregistration.
The bank account. Polish banks apply full anti-money-laundering identification and most still expect a board member to attend a branch with a passport, though several now onboard remotely using a qualified electronic signature. Two points argue for a genuine Polish account: tax is paid through the mikrorachunek podatkowy, the individual tax micro-account generated from the company's NIP, and only accounts held with Polish banks or credit unions and reported to the tax office appear on the VAT white list — a foreign IBAN exposes your Polish customers to the penalties described next.
5.VAT Registration, VAT-UE and the White List with Split Payment
Registration. VAT is charged at a standard 23%, with reduced rates of 8% and 5% and zero-rating for exports and intra-Community supplies. A company registers on form VAT-R before its first taxable sale. Registration is not automatic: the tax office verifies that the business is real and routinely asks for the lease, contracts, bank details and a description of the activity, so allow days to several weeks. A small-business exemption covers annual turnover up to PLN 200,000, but it is closed to several advisory and legal activities and to businesses without an establishment in Poland.
VAT-UE. Trading with other member states requires a separate entry on the same form, which activates the PL prefix and publishes the number in the EU VIES database. It must be in place before the first intra-Community acquisition or supply, and it brings a monthly recapitulative statement (informacja podsumowująca) by the 25th.
The white list. The tax administration publishes the biała lista podatników VAT, showing each taxpayer's VAT status and the bank accounts it has reported. Paying PLN 15,000 or more to an account that is not on the list costs the payer twice: the expense is not deductible for corporate income tax, and the payer becomes jointly liable for the supplier's VAT. Both can be avoided by filing a ZAW-NR notification within seven days of the transfer, but automated verification at the moment of payment is the sensible course.
Split payment. The mechanizm podzielonej płatności is mandatory on invoices of PLN 15,000 gross or more covering the goods and services listed in Annex 15 of the VAT Act — construction, electronics, steel, fuels. The VAT element lands in a separate VAT account usable only for VAT, other taxes, customs duties and social contributions.
6.Corporate Income Tax: 19%, the 9% Rate and Estonian CIT
The standard rate is 19% on the worldwide income of a Polish resident company. Residence follows the seat or the place of management, so a sp. z o.o. managed entirely from abroad can create a tax presence in the manager's country too — board governance deserves thought at the structuring stage.
The 9% reduced rate applies to income other than capital gains for a small taxpayer, whose gross sales revenue including VAT did not exceed the PLN equivalent of EUR 2 million in the previous year, provided current-year net revenue stays within the same ceiling. New companies may use it in their first tax year, subject to anti-abuse rules excluding entities created out of conversions or contributions of an existing business.
Estonian CIT. The ryczałt od dochodów spółek is the most interesting feature of the system for a reinvesting business: no corporate tax is due until profit is distributed, so earnings that fund equipment, hiring or working capital are simply not taxed. On distribution the rate is 10% for small taxpayers and starters and 20% for others, and because the shareholder deducts part of the company's tax from the 19% dividend tax, the combined effective burden falls to roughly 20% and 25% respectively. Conditions matter: only individual shareholders, no shareholdings in other entities, at least three employees other than shareholders (relaxed for new companies), and passive income in the minority. The investment-spending requirement of the first version was removed in 2022.
Dividends to a foreign parent bear 19% withholding tax, commonly reduced by treaty or eliminated under the EU Parent-Subsidiary rules, with a pay-and-refund mechanism above PLN 2 million a year per recipient. A separate minimum income tax targets companies with sustained losses or very low profitability and took practical effect for years from 2024.
7.IP Box, R&D Relief and Incentives for Technology Businesses
Poland's incentive package is one reason software and engineering groups choose it over cheaper neighbours.
IP Box. Income from qualified intellectual property — patents, protection rights and, in practice above all, copyright in computer programs — created, developed or improved through the company's own research and development is taxed at 5% rather than 19%. The relief is claimed in the annual return, not in monthly advances, and it stands or falls on documentation: separate records identifying revenue, costs and income for each qualifying asset, plus evidence of the R&D work behind it. Software houses with their own product, and groups that centralise development in a Polish subsidiary, are the typical beneficiaries.
R&D relief (ulga B+R). Eligible development costs are deducted twice — once as ordinary costs and again as a relief worth 100% of qualifying costs, and 200% of eligible employee costs, with a wider 200% band for accredited research and development centres. Since 2022 the two reliefs may be combined, so the same income can take the R&D deduction and then be taxed at the IP Box rate. Where a young company has no taxable income to absorb the relief, a cash refund mechanism exists for the first years of trading.
The Polish Investment Zone. Capital projects can obtain a decision on support granting a corporate income tax exemption for ten to fifteen years, available anywhere in the country rather than only in the former special economic zones. The exempt amount is a percentage of the qualifying investment, set by the regional aid map and increased for smaller enterprises. Further reliefs cover robotisation, prototypes and market expansion — most claimed annually, on evidence gathered during the year rather than after it.
8.ZUS Social Insurance, Payroll and the Sole Shareholder
Employer registration. A company that hires becomes a contribution payer with ZUS (Zakład Ubezpieczeń Społecznych), the social insurance institution. Registration follows from the KRS and NIP-8 chain; each employee must be notified within seven days of starting work, with monthly declarations and payments thereafter.
The cost of employment. On top of gross salary the employer pays roughly 20.5%: pension 9.76%, disability 6.5%, an accident contribution of 0.67% to 3.33% depending on risk class, plus the labour fund and guaranteed benefits fund. The employee bears a further 13.71% of gross and a 9% health contribution. Alongside the standard umowa o pracę (employment contract), Polish practice uses the umowa zlecenia (civil-law mandate) and independent contractor arrangements; each has a different contribution profile, and treating a genuine employee as a contractor is a recognised audit risk.
The sole shareholder trap. For social insurance purposes the sole shareholder of a sp. z o.o. counts as a person conducting business activity and must pay full social and health contributions personally, whether or not the company pays any salary. Two genuine shareholders fall outside the rule — but ZUS and the courts have repeatedly disregarded arrangements where a second shareholder holds a token 1% purely to avoid the charge, so both the stake and the involvement should be real.
Board members. Remuneration paid purely on an appointment resolution (powołanie), with no employment or mandate contract, carries no social insurance contributions, though since 2022 it does attract the 9% health contribution. For a board member who is not tax resident in Poland it is generally subject to a flat 20% withholding tax, subject to the applicable double tax treaty.
9.Annual Obligations, KSeF e-Invoicing and Residence Rights
Books and financial statements. Every company keeps full double-entry books under the Polish Accounting Act, in Polish and in złoty. The annual financial statement is prepared within three months of the balance sheet date, approved by the shareholders within six months and filed electronically to the KRS Repository of Financial Documents within 15 days of approval. Filing is free, the statement must be in the prescribed structured XML format and signed electronically by the board, and the result is public. An independent audit becomes compulsory only once the company crosses two of three size thresholds, which were raised for financial years beginning in 2025.
Tax filings. The annual CIT-8 return is filed electronically by the end of the third month after the year end — 31 March for a calendar-year company — with advances paid monthly, or quarterly for small and starting taxpayers. VAT runs through JPK_V7M or JPK_V7K, a single structured file combining the return and the underlying records, submitted by the 25th of the following month; uncorrected errors carry a penalty each. Structured reporting of the accounting books themselves (JPK_CIT) is being phased in from 2025, largest taxpayers first.
KSeF. The Krajowy System e-Faktur, the national e-invoicing platform, issues and stores invoices in one government system. Voluntary use is already available and a phased mandatory rollout is planned, large taxpayers first. The timetable has been rescheduled more than once, so confirm current dates before a software migration — but assume structured e-invoicing will become the norm.
Residence rights. Owning a Polish company gives no right to live in Poland: EU and EEA nationals move freely, others need a visa or a residence permit. A board member serving in Poland for more than six months in twelve generally needs a type B work permit, and the temporary residence permit for business activity requires the company to show either income of at least twelve average monthly salaries in the preceding year or two full-time employees who need no work permit. The company is a strong foundation for such an application, not a substitute for one.
Three Decades of Uninterrupted Growth
Poland produces roughly EUR 800 billion of annual output, making it the largest economy in Central Europe and the sixth largest in the European Union. It grew every single year from 1992 until the pandemic and was the only EU member state to avoid recession in 2009 — a record no other European economy can match. The country keeps its own currency, the złoty, which gives monetary flexibility alongside full single-market membership.
Manufacturing and Nearshoring
Industry accounts for a far larger share of output than in most of Western Europe. Poland is Europe's leading producer of household appliances, a major supplier of automotive components and batteries, and one of the world's largest furniture exporters. Costs well below the eurozone average, EU regulatory standards and short road distances to Germany have made it the principal destination for companies shortening supply chains out of Asia.
IT and Business Services
Around 400,000 people work in the modern business services sector, in shared service centres, IT and research operations concentrated in Kraków, Warsaw, Wrocław, the Tri-City and Katowice. A deep pipeline of engineering and mathematics graduates, an established reputation in software development and the IP Box regime have drawn the European technology and back-office functions of a long list of global groups.
EU Funds and a Central European Logistics Hub
Poland is the largest beneficiary of EU cohesion policy, with tens of billions of euros allocated for 2021-2027 alongside national recovery funding, financing motorways, rail upgrades and energy investment built out over two decades. Sitting on the Union's eastern frontier with Baltic deep-water ports at Gdańsk and Gdynia, the largest international road haulage fleet in the EU and rail gateways handling China-Europe freight, it functions as the distribution hub for the whole of Central and Eastern Europe.